Actual cash value vs. replacement cost: the warning every policyholder needs
Understand actual cash value vs. replacement cost and avoid costly surprises after fire, storm, theft, or property damage claims.
Actual Cash Value vs Replacement Cost: What Policyholders Should Know
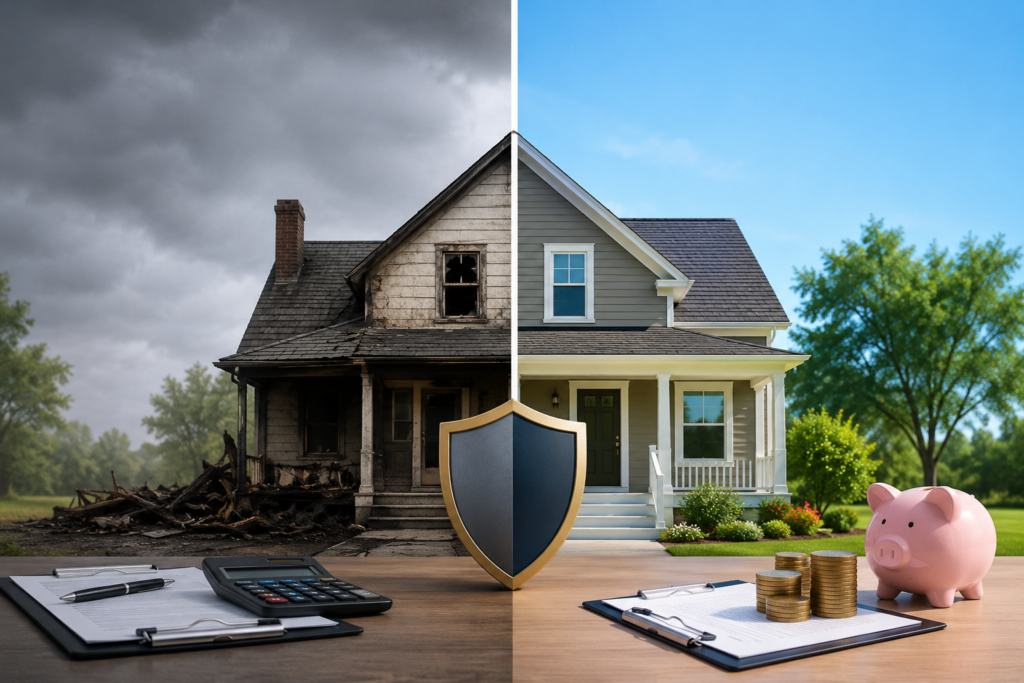
Many homeowners and renters in the United States assume their insurance policy will fully protect them after a fire, storm, theft, or other major loss. Unfortunately, that assumption often proves wrong when the claim is finally filed.
One of the biggest reasons policyholders end up shocked, frustrated, and financially exposed comes down to a detail hidden deep inside the policy: Actual cash value vs. replacement cost.
At first glance, the difference may seem technical or minor. In reality, it can determine whether you receive enough money to rebuild your life, or whether you are forced to pay thousands of dollars out of pocket after a disaster.
Understanding how these two types of coverage work is one of the most important financial protection decisions any homeowner, renter, or property owner can make.
What does actual cash value mean in insurance?
Actual cash value (ACV) is the amount your insurer believes your damaged or stolen property was worth at the time of the loss.
The key detail is this:
Actual cash value includes depreciation.
That means the insurance company subtracts value based on age, wear and tear, condition, and expected lifespan.
For example:
- You bought a TV five years ago for $1,500
- Today, a similar new TV costs $1,800
- Because your old TV depreciated over time, the insurer may value it at only $400 or $500
Instead of receiving enough money to buy a new replacement, you receive only the depreciated value.
This is why many policyholders are caught off guard after filing claims.
How depreciation affects your payout
Insurance companies use depreciation schedules to estimate how much value an item has lost over time.
Commonly depreciated items include:
- Electronics
- Roofs
- Furniture
- Appliances
- Flooring
- Clothing
- Personal belongings
A roof is one of the most important examples.
Imagine your roof originally cost $20,000 and is now 15 years old. Even if a storm completely destroys it, an ACV policy might only reimburse $7,000 to $10,000 after depreciation.
The remaining amount comes out of your pocket.
According to the Insurance Information Institute, many homeowners misunderstand how depreciation impacts claims until after major damage occurs.
What is replacement cost coverage?
Replacement cost coverage works differently.
Instead of paying the depreciated value, the insurer pays what it currently costs to repair or replace the item with a similar new version.
This type of policy is designed to help you recover financially without absorbing massive replacement expenses yourself.
Using the same TV example:
- Original purchase price: $1,500
- Current replacement price: $1,800
- Replacement cost coverage payout: approximately $1,800 (minus deductible)
That difference becomes even more significant for homes, roofs, and major personal property losses.
Replacement cost coverage is generally more expensive, but it provides much stronger financial protection.
Actual cash value vs. replacement cost: the core differences
| Feature | Actual Cash Value | Replacement Cost |
|---|---|---|
| Includes depreciation | Yes | No |
| Lower premiums | Usually | Usually higher |
| Out-of-pocket costs after claim | Higher | Lower |
| Pays current replacement prices | No | Yes |
| Better for older property | Sometimes | Usually |
| Financial protection level | Lower | Higher |
For many policyholders, the cheaper premium of ACV coverage seems attractive at first. However, after inflation, rising labor costs, and higher construction expenses in the United States, replacement cost protection has become increasingly important.
Why this issue matters more today
In recent years, rebuilding costs across the U.S. have increased dramatically.
According to the National Association of Home Builders, construction material prices and labor shortages have significantly increased rebuilding expenses after disasters.
At the same time:
- Severe weather events are becoming more frequent
- Supply chain disruptions increase repair delays
- Home replacement costs are rising faster than many policy updates
This creates a dangerous gap.
A policyholder may believe they have sufficient coverage, only to discover their payout falls far short of current rebuilding costs.
This is one of the biggest financial risks hidden inside many insurance policies today.
The most common mistake policyholders make
The most common mistake is focusing only on monthly premiums instead of claim outcomes.
Many consumers compare insurance quotes like this:
- Policy A: cheaper premium
- Policy B: higher premium
Without examining whether the policy uses:
- Actual cash value
- Replacement cost
- Extended replacement cost
- Guaranteed replacement cost
That small detail can completely change the financial outcome after a loss.
Real-world example
Imagine two neighbors suffer identical fire damage.
Homeowner A has actual cash value coverage
- Older roof
- Older flooring
- Older appliances
The insurer subtracts depreciation and pays significantly less than replacement costs.
Result:
- Large out-of-pocket expenses
- Delayed repairs
- Financial hardship
Homeowner B has replacement cost coverage
The insurer covers the current rebuilding and replacement costs for similar materials and items.
Result:
- Faster recovery
- Less financial stress
- Better long-term protection
The premium difference between those policies may have been only a few dollars per month.
How insurers calculate depreciation
Insurance companies evaluate several factors when determining ACV payouts.
These often include:
| Factor | Impact on Value |
|---|---|
| Age | Older items lose value |
| Condition | Damage or wear lowers payout |
| Useful lifespan | Shorter remaining life reduces value |
| Obsolescence | Older technology depreciates faster |
| Market value | Current demand may affect pricing |
Unfortunately, depreciation calculations can sometimes become a source of disputes between policyholders and insurers.
The National Association of Insurance Commissioners (NAIC) recommends carefully reviewing policy language and documenting personal property to avoid claim disagreements.
When actual cash value may still make sense
Despite its drawbacks, ACV coverage is not always a bad option.
In some situations, it may be appropriate:
Older homes with lower market value
If rebuilding the property is not a priority, ACV may reduce premium costs.
Rental properties
Some landlords choose ACV to lower insurance expenses, especially for older structures.
Budget constraints
For some families, lower premiums may be the only affordable option.
However, policyholders must fully understand the tradeoff:
Lower monthly premiums can create much higher financial exposure later.
What many policyholders do not realize about replacement cost
Replacement cost coverage is often misunderstood as “unlimited protection.”
That is not always true.
Many policies include important conditions such as:
- Replacement must actually occur before full reimbursement
- Coverage caps still apply
- Certain belongings may have sub-limits
- Luxury upgrades may not be covered
- Code upgrade costs may require endorsements
For example, if local building codes changed since your home was built, rebuilding to current standards may cost significantly more.
Some insurers offer:
- Extended replacement cost
- Guaranteed replacement cost
- Ordinance or law coverage
These add-ons can provide stronger protection in high-inflation or disaster-prone areas.
How to review your policy correctly
Most people never fully read their homeowners insurance policy. Tis understandable, policies are long and highly technical.
Still, reviewing a few critical sections can prevent major financial surprises.
Step 1: Identify the valuation method
Look for terms such as:
- Actual cash value
- Replacement cost value (RCV)
- Replacement cost loss settlement
This section determines how claims are paid.
Step 2: Review dwelling coverage limits
Make sure your dwelling coverage reflects current rebuilding costs, not just home market value.
These numbers are very different.
Step 3: Check personal property coverage
Some policies automatically default personal belongings to ACV even if the home itself has replacement cost coverage.
This catches many homeowners by surprise.
Step 4: Ask about endorsements
Ask your insurance agent about:
- Extended replacement cost
- Water backup coverage
- Ordinance and law coverage
- Scheduled personal property riders
Step 5: Update your policy annually
Home renovation projects, inflation, and rising construction costs can quickly make old limits outdated.
Why roof claims are becoming a major controversy
Across the United States, many insurers have shifted older roofs from replacement cost coverage to actual cash value settlements.
This trend has become more common in states affected by hurricanes, hail, and severe storms.
Some homeowners only discover this after filing a claim.
For example:
- A 20-year-old roof may receive heavy depreciation deductions
- The insurer pays far less than replacement cost
- The homeowner must fund the difference
Given rising roofing costs nationwide, this issue has become increasingly important.
The Federal Emergency Management Agency (FEMA) also encourages homeowners to review insurance protections regularly before disasters occur.
Final thoughts: the insurance detail that can change everything
The debate around Actual cash value vs. replacement cost is not just technical insurance language. It directly affects how much financial protection you truly have after a disaster.
Many policyholders only learn the difference after suffering a devastating loss. By then, it is too late to change coverage.
That is why reviewing your policy before disaster strikes is critical.
A cheaper premium may save money today, but inadequate coverage can cost tens of thousands tomorrow.
Taking time now to understand your policy, review your limits, and ask better questions can make the difference between financial recovery and financial hardship after a major claim.
Related content
What to review in your insurance policies every
Learn why reviewing your insurance policies yearly can help prevent claim denials, coverage gaps, and major out-of-pocket expenses.
Keep reading * You will remain on the current websiteFrequently asked questions about actual cash value vs. replacement cost
Not always. Replacement cost usually offers stronger financial protection, but it also comes with higher premiums.
ACV reduces insurer payouts by accounting for depreciation. This lowers risk for insurance companies and often results in cheaper premiums for consumers.
In many cases, yes. However, eligibility depends on the insurer, property condition, roof age, and policy type.
No. Policies still have limits, exclusions, deductibles, and conditions. Some expenses may require additional endorsements.
Older roofs carry higher risk for insurers. Some companies apply ACV settlements specifically to roofs while offering replacement cost for the rest of the property.