Overview of the Fire Strategy: What It Is and How It Works
Understand the FIRE strategy, how it works, and how financial independence can change the way you plan your financial future.
How a Fire Strategy Works in Practice
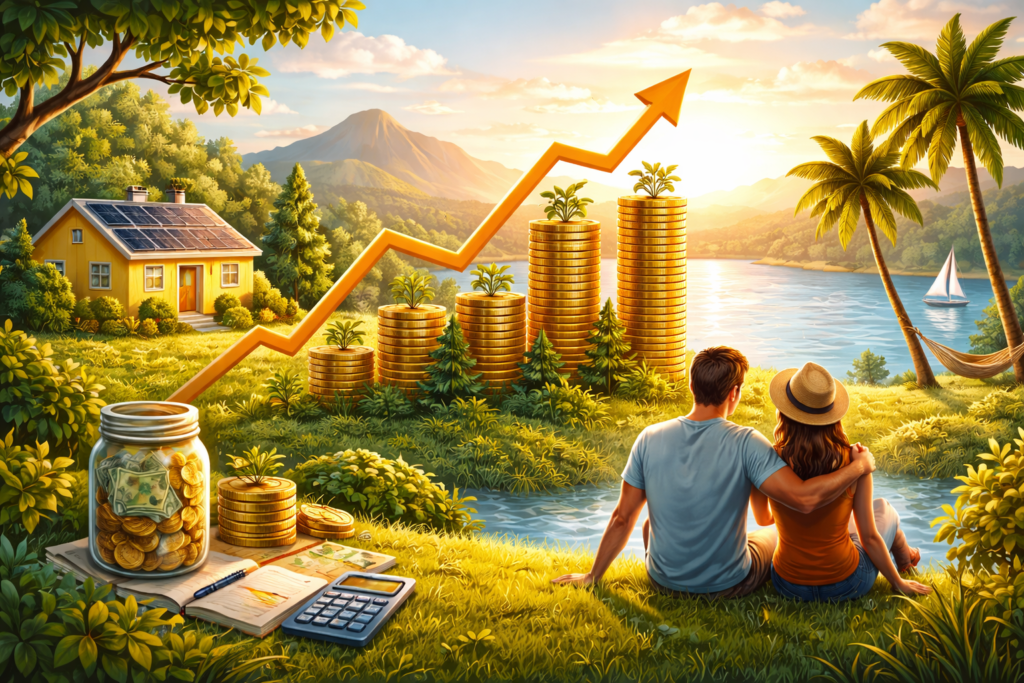
The FIRE strategy has gained significant attention in the United States over the past decade, especially among professionals seeking greater control over their time and financial decisions.
FIRE stands for Financial Independence, Retire Early, and while the name suggests an early exit from work, the concept is broader than simply retiring young. At its core, FIRE is about building enough financial security to make work optional.
The goal is to reach a point where investment income can fully cover living expenses, allowing individuals to choose how they spend their time without financial pressure.
What Financial Independence Really Means
Financial independence does not necessarily mean never working again. Instead, it means having enough assets and passive income to support your lifestyle without depending on a paycheck.
For many people pursuing FIRE, this creates freedom to change careers, start a business, work part-time, or focus on personal projects.
In the United States, where retirement often depends on personal savings rather than government programs, financial independence offers a sense of stability and autonomy.
It shifts the focus from accumulating wealth for its own sake to designing a life aligned with personal values and priorities.
How the FIRE Strategy Works in Practice
The FIRE strategy is built on three interconnected pillars: high savings rates, disciplined spending, and consistent investing.
Together, these elements accelerate wealth accumulation and shorten the timeline to financial independence.
Savings play a central role. While the average American household saves a modest portion of its income, FIRE followers often aim to save 40%, 50%, or even more.
This is achieved not only by increasing income but also by making deliberate choices about expenses, prioritizing value over convenience or status.
Investing is the engine that turns savings into long-term financial independence.
Most FIRE strategies rely on diversified investments such as index funds, retirement accounts like 401(k)s and IRAs, and taxable brokerage accounts. The objective is steady, long-term growth rather than short-term speculation.
The 4% Rule and Passive Income
One of the most commonly referenced concepts within the FIRE community is the 4% rule.
This guideline suggests that if you can live on 4% of your invested assets annually, your portfolio may last indefinitely under typical market conditions.
While not a guarantee, it provides a simple framework for estimating how much wealth is needed to achieve financial independence.
For example, someone who wants to spend $60,000 per year would aim for an investment portfolio of approximately $1.5 million. Passive income from dividends, interest, and capital gains then replaces active income from work.
In the U.S., this approach is often combined with tax-advantaged accounts, employer matching contributions, and long-term market participation to improve sustainability and tax efficiency.
Different Approaches to FIRE
Not everyone pursues FIRE in the same way. Some individuals adopt a minimalist lifestyle to reach independence as quickly as possible.
Variations such as Lean FIRE, Fat FIRE, and Coast FIRE reflect different comfort levels, spending goals, and timelines.
What these approaches share is intentionality. FIRE is less about deprivation and more about making conscious trade-offs.
It encourages individuals to question whether current spending aligns with long-term goals and personal fulfillment.
Benefits and Challenges of the FIRE Strategy
The benefits of the FIRE strategy go beyond early retirement. Many people report reduced financial stress, clearer priorities, and improved decision-making once they adopt a FIRE mindset.
The focus on long-term planning can also lead to better financial habits and resilience during economic uncertainty.
However, the strategy also comes with challenges. High savings rates require discipline and consistency, and market volatility can test emotional resilience.
Additionally, healthcare costs, inflation, and lifestyle changes must be carefully considered, especially in the U.S. system where these factors can significantly impact long-term plans.
Is the FIRE Strategy Right for You?
The FIRE strategy is not a one size fits all solution. It requires a willingness to plan ahead, adapt spending habits, and stay committed over time.
For some, the appeal lies in retiring early; for others, it is about gaining flexibility and peace of mind long before traditional retirement age.
FIRE should be viewed as a framework, not a rigid formula. By understanding how it works and thoughtfully applying its principles.
Related content
Why 2026 Could Change Your Portfolio Rebalancing
Review your investment portfolio before 2026 begins. Learn how year end rebalancing can help manage risk.
Keep reading * You will remain on the current website Why 2026 Could Change Your Portfolio Rebalancing
Keep reading You will remain on the current website