Mortgage Recast or Refinance: Which Option Fits Your Financial Goals?
Mortgage recast or refinance? Compare costs, benefits, and scenarios to choose the best option for lowering payments.
Understand which is the best option between renegotiating or refinancing your mortgage
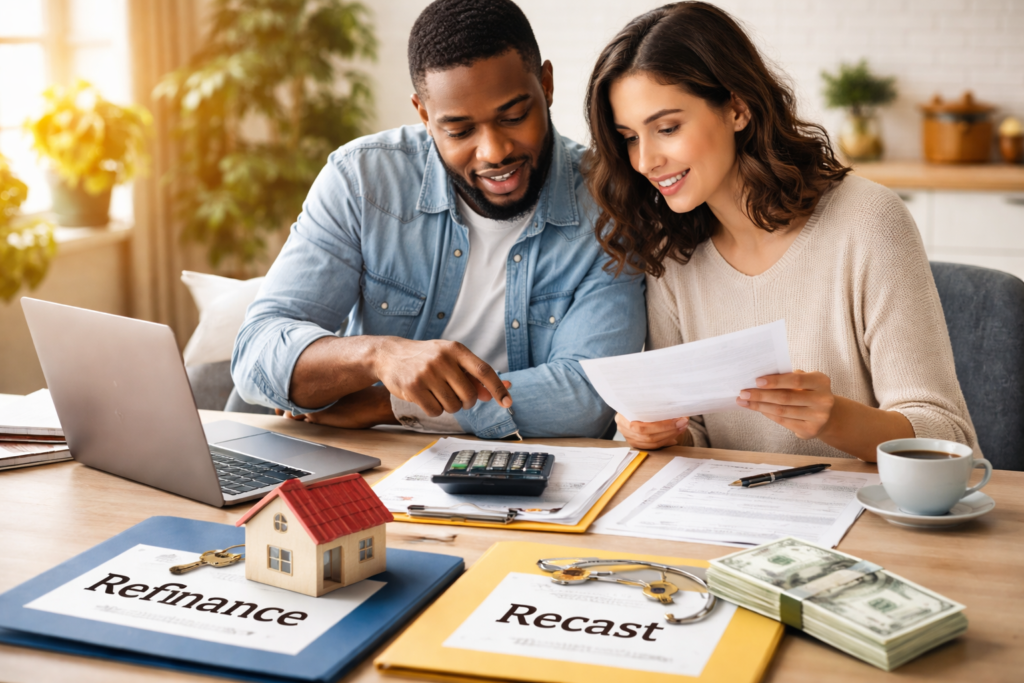
When managing a home loan in the United States, many homeowners eventually ask the same question: Is there a smarter way to reduce my monthly mortgage payment or improve my long-term financial outlook?
Two common strategies often come up, mortgage recast and mortgage refinance. While they may seem similar at first glance, each option serves a different purpose and fits different financial goals.
Understanding how they work, their costs, and when each makes sense can help you make a confident and informed decision.
What Is a Mortgage Recast?
A mortgage recast allows you to lower your monthly payment by making a large lump-sum payment toward your principal balance.
After this payment, the lender recalculates your monthly payments based on the reduced balance, while keeping the same interest rate and loan term.
Mortgage recasting is typically available only for conventional loans and must be approved by your lender.
Most lenders require a minimum lump-sum payment, often between $5,000 and $20,000, and charge a relatively small administrative fee.
Key characteristics of a mortgage recast:
- No change to interest rate;
- No change to loan term;
- Lower monthly payment;
- Minimal fees;
- Faster and simpler process than refinancing.
This option works well for homeowners who receive a financial windfall, such as a bonus, inheritance, or proceeds from selling another property, and want immediate payment relief without restarting their mortgage.
What Is a Mortgage Refinance?
A mortgage refinance replaces your existing loan with a new mortgage, usually with a different interest rate, loan term, or both.
Refinancing can reduce your monthly payment, lower your interest rate, shorten your loan term, or allow you to access home equity through cash-out refinancing.
Unlike a recast, refinancing requires a full loan application, including credit checks, income verification, and closing costs, often ranging from 2% to 6% of the loan amount.
Key characteristics of a refinance:
- Potentially lower interest rate;
- Option to change loan term (e.g., 30-year to 15-year);
- Higher upfront costs;
- More paperwork and longer timeline;
- Can significantly reduce total interest paid over time.
Refinancing is often most beneficial when interest rates drop meaningfully or when your financial profile has improved since you first took out your mortgage.
Mortgage Recast vs. Refinance: Key Differences
While both options can lower monthly payments, the strategy behind them is very different.
A mortgage recast focuses on cash flow relief. It is ideal if you already have a favorable interest rate and simply want to reduce your payment without changing the structure of your loan.
A refinance, on the other hand, is a long-term optimization tool.
It can reduce the total cost of your mortgage, help you pay off your home faster, or align your loan with new financial priorities, but it comes with higher upfront costs.
Which Option Fits Your Financial Goals?
Choosing between a recast and a refinance depends on your current situation and what you want to achieve.
A mortgage recast may be the right choice if you:
- Have extra cash available;
- Already have a low interest rate;
- Want lower monthly payments without extending your loan;
- Prefer minimal fees and a simple process.
A mortgage refinance may be better if you:
- Can secure a significantly lower interest rate;
- Want to shorten or extend your loan term;
- Need to access home equity;
- Plan to stay in your home long enough to offset closing costs.
Cost and Timing Considerations
One of the biggest differences between the two options is cost. Mortgage recasts are generally inexpensive and quick, often completed within a few weeks.
Refinancing, while potentially more impactful over the long run, requires careful cost-benefit analysis to ensure the savings outweigh the upfront expenses.
Timing also matters. In a high-interest-rate environment, recasting can be more attractive. When rates fall, refinancing often becomes the stronger option.
Final Thoughts
There is no one-size-fits-all answer when deciding between a mortgage recast and a refinance. Both tools can support smart financial planning when used strategically.
The key is to align the option you choose with your broader financial goals, whether that means improving monthly cash flow, reducing long-term interest costs, or increasing flexibility in your budget.
Before making a decision, review your loan terms, assess your available cash, and consider speaking with a mortgage professional who can help you evaluate both scenarios.
A well-timed choice today can create meaningful financial breathing room for years to come.
Related content
How to negotiate your insurance
Save money on insurance in the United States without sacrificing coverage.
Keep reading * You will remain on the current website